All Categories
Featured

Emerging Stock Trading Patterns for 2026
Table of Contents
Dangers are tilted to the disadvantage. In the occasion of an extended conflict, the present effect on the area will be compoundedthrough raised energy and food prices, decreasing trade, tourism and remittances, increased fiscal pressures, and displacement. "The present crisis is a stark tip of the work ahead for the area: not just to weather shocks, however to reconstruct more resilient economies with stronger macroeconomic principles, innovate and enhance governance, buy facilities, and increase employment-creating sectors," stated.
With peace and the best action, countries can construct the organizations, capabilities and competitive sectors that produce opportunities for individuals." With this long-term vision in mind, the report takes a close look at the region's capacity for commercial policy government actions to increase tactical service activity as a motorist of financial growth and task development.

Governments in the region have actually adopted commercial policy at a high rate in the last years, often through sovereign wealth funds and state-owned business, but the results have been mixed. The report highlights the vital need for strong organizations and careful targeting of policies. "As nations face the heavy toll of today conflict, it is essential to also not lose sight of the work required for long-lasting peace and success," said.
Driving Non-Oil Success through Strategic Diversification
Q2 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the area prepared directly for the finance occupation. The GCC economy deals with a significant contraction this year pending details of the US-Iran agreement to end the war. We expect energy flows, tourism and investor belief to gradually normalise as war disruptions subside.

The interim arrangement in between the United States and Iran is a considerable action towards reaching a full-blown deal. A full go back to normality in the Strait of Hormuz will likely take time, however the threat of a recession-inducing oil rate spike has decreased. Global GDP is expected to grow by 2.4% this year, 0.2 ppt less than we forecasted 3 months ago, and 3.1% in 2027.
Upcoming GCC Investment Trends for 2026 Global MarketsWe anticipate a 4.1% contraction in Middle East GDP this year (versus forecasted 3.6% growth before the war), higher than the decline in the first year of the Covid pandemic. Kuwait, Iran, Iraq and Qatar stick out as the hardest hit, owing to their inability to avoid the disruption to local shipping, war-driven facilities damage and tourism losses.
Our 2026 outlook for the GCC is weaker than three months earlier, with GDP forecast to contract by 2.4% compared to a 0.2% decline forecasted previously. We anticipate Oman and Saudi Arabia to be the least adversely impacted by the fallout from the conflict, with both economies continuing to expand this year.
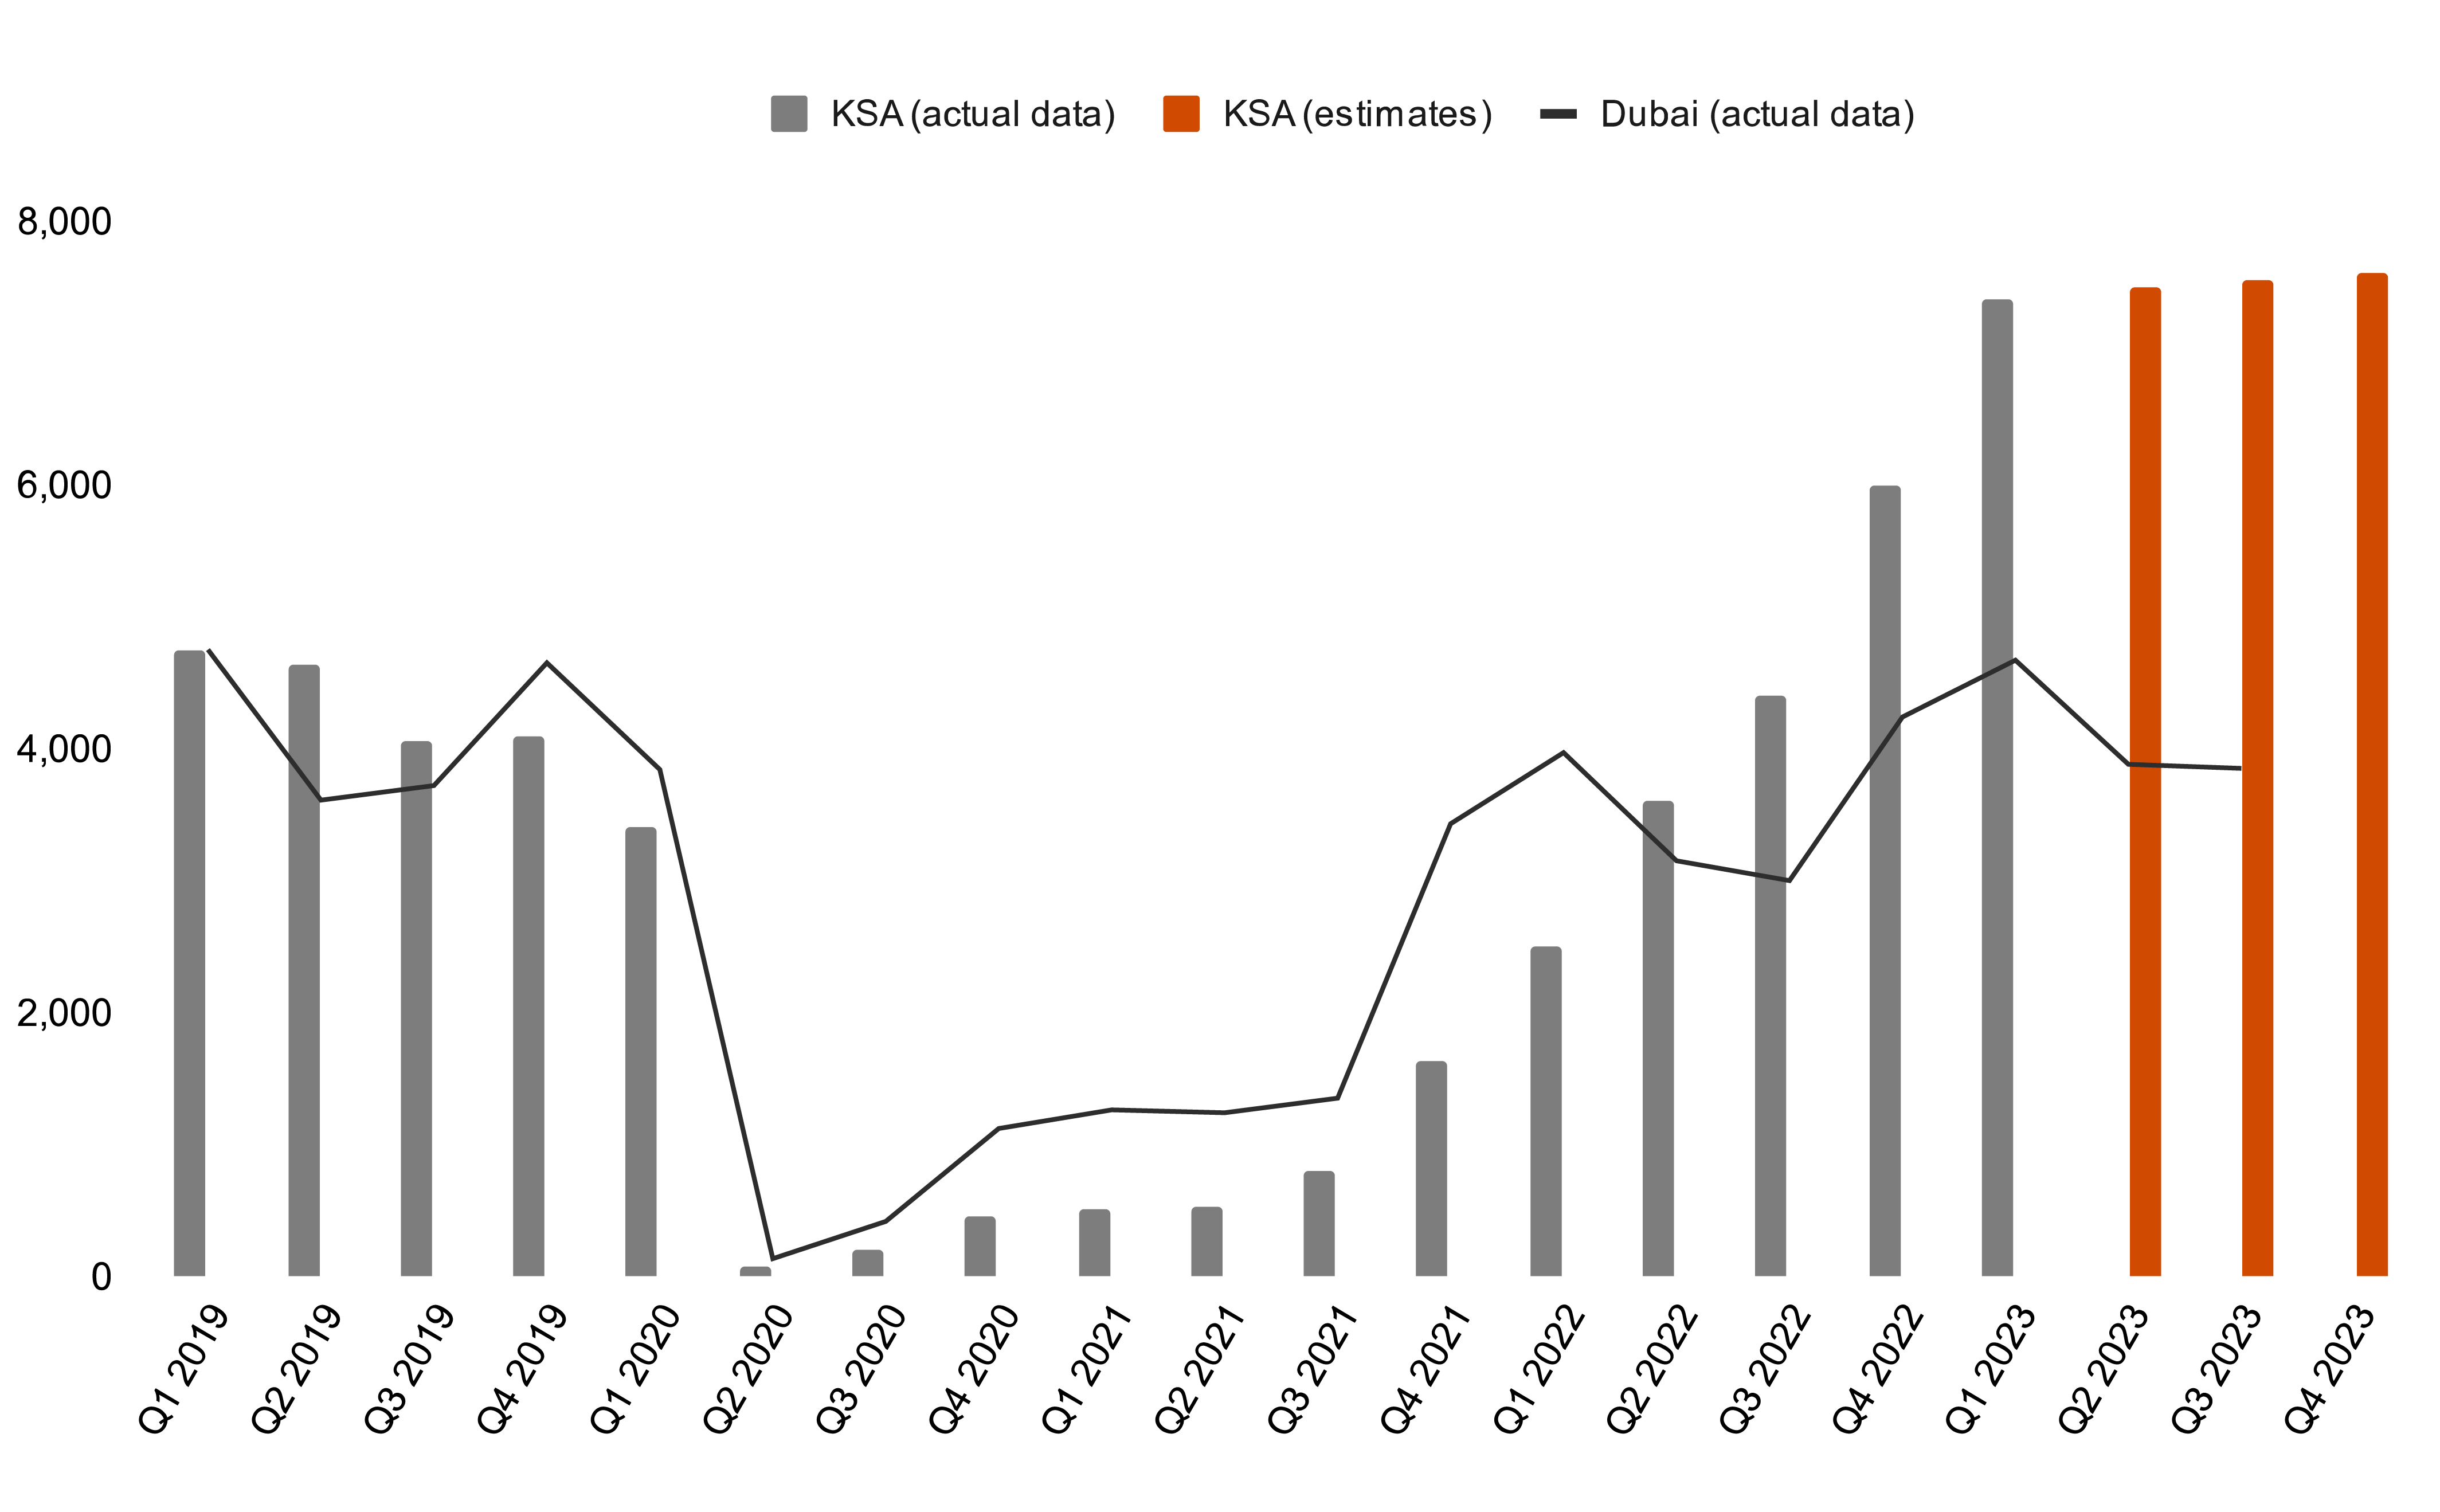
The financial damage incurred in the last couple of months is considerable. Saudi GDP information for Q1 showed development slowed to 3% y/y, with non-oil activities broadening by 2.9%, the weakest speed considering that the Covid pandemic. On a seasonally adjusted basis, GDP contracted 1.2% q/q, driven by a 6.8% fall in oil activities as the Strait of Hormuz disturbance struck late in the quarter.
Analyzing Regional Investment Resilience for 2026
Aside from Oman, all GCC producers along with Iran and Iraq have actually suffered comprehensive oil and gas production losses since the start of the conflict. May data show regional production almost cut in half from pre-war levels, with the decline deepening relative to March and April. Rerouting efforts, consisting of by Saudi Arabia through the East-West Pipeline and the UAE through the Habshan-Fujairah pipeline, have assisted prevent an even larger plunge in output.
We anticipate GCC oil sector output to agreement by 14.5% this year, which will mark the steepest decline in a number of decades. We then anticipate a 23.5% rebound next year, driven mostly by normalisation from a badly depressed base. On the other hand, oil prices have been unstable, reducing below $85 per barrel as the interim agreement was announced.
In the medium term, we expect oil costs to be a little lower than our pre-war baseline, as the UAE's departure from OPEC+ enables for a gradual boost in its output towards the 5mn barrel each day production target when trade normalises. Versus this background, the UAE will speed up the building of a new West-East pipeline that ought to double the capability of export through Fujairah.
The May PMI surveys reported output development reaching its strongest level in three months, driven mainly by improved domestic need. They remain listed below long-run averages, with weak export orders and price pressures from greater material and transport expenses are a typical theme. Overall, we expect a 1.1% contraction in GCC non-energy sectors this year (compared to 4.2% growth pre-war) and a progressive recovery over the remainder of the years.

Table of Contents
Latest Posts
Top Global Investment Trends within the GCC Economy

Actionable Tips for Entering 2026 Foreign Investment Opportunities
Refining Capital Strategies for the Next-Gen GCC Economy
Latest Posts
Top Global Investment Trends within the GCC Economy
Actionable Tips for Entering 2026 Foreign Investment Opportunities
Refining Capital Strategies for the Next-Gen GCC Economy